Supplemental Plans — Critical Illness
Critical Illness Insurance: A Cash Benefit When a Serious Diagnosis Changes Everything
A diagnosis like cancer, a heart attack, or a stroke can bring costs your primary coverage doesn’t fully absorb. Critical illness insurance pays a lump-sum cash benefit directly to you, to use however you need. As an independent agency, we compare plans from multiple carriers to find one that fits your situation, at no cost to you.
Get My Free Critical Illness ConsultationCritical illness basics
What Is a Critical Illness Plan?
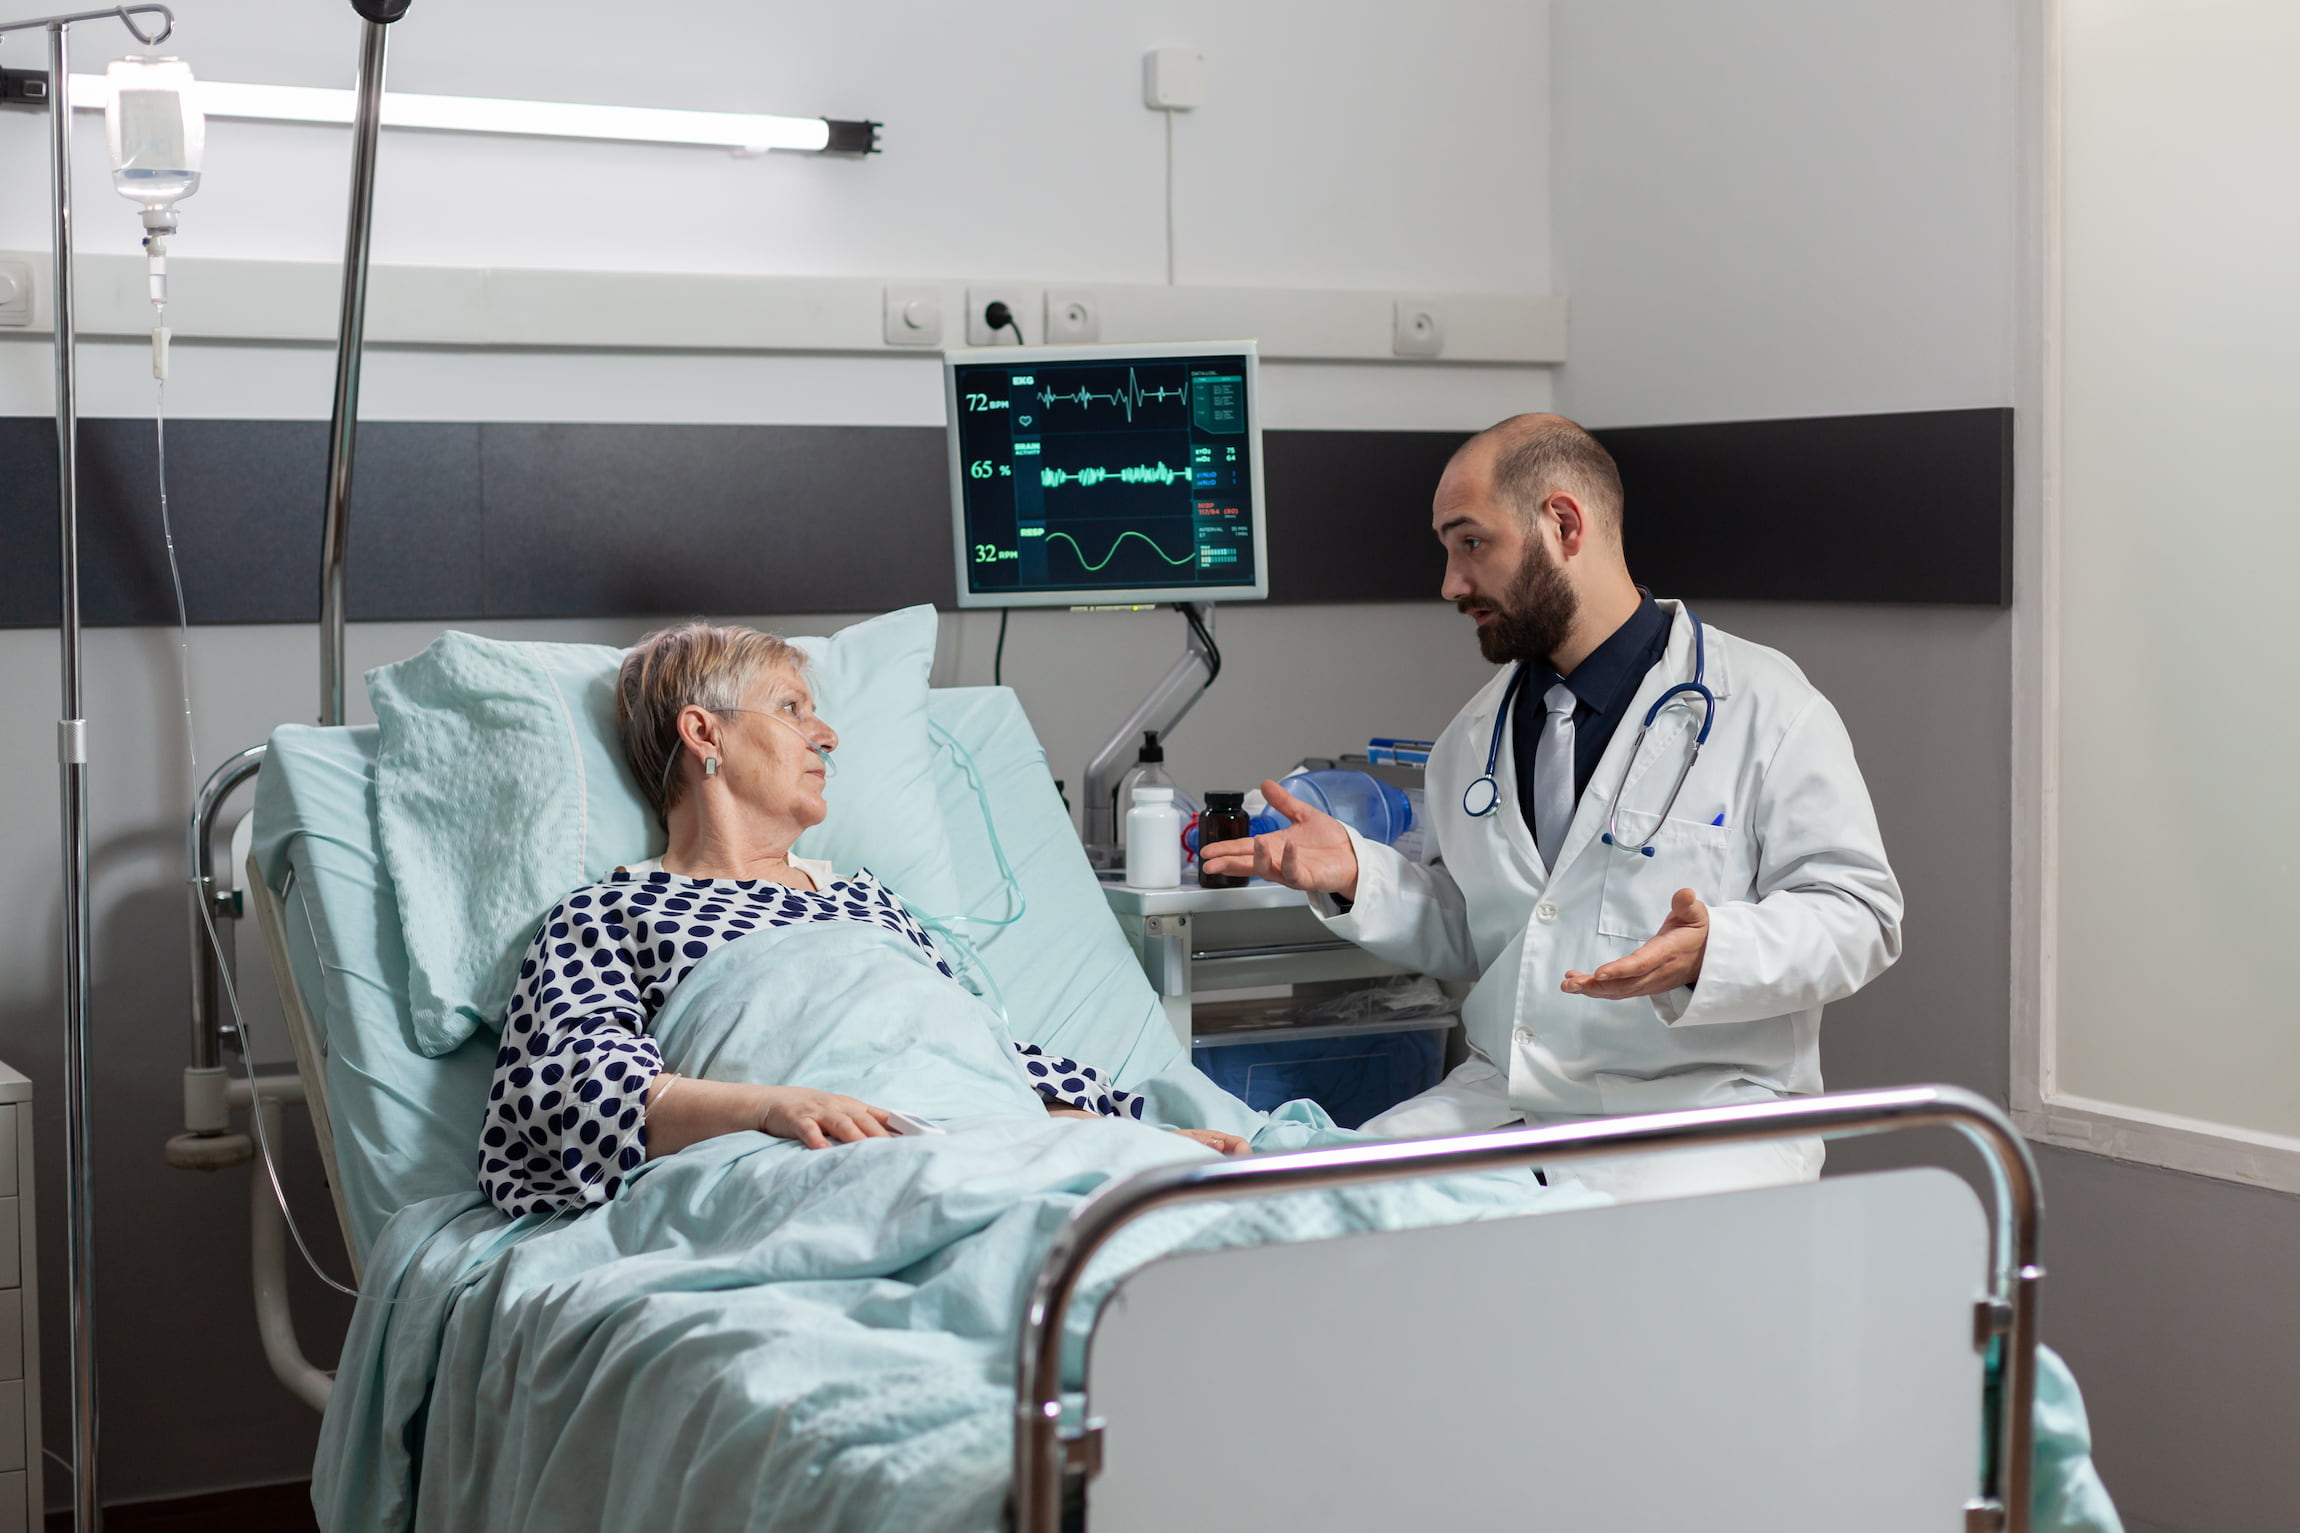
Critical illness insurance is a supplemental policy that pays a lump-sum cash benefit directly to you if you’re diagnosed with a covered condition, such as cancer, a heart attack, or a stroke. This benefit is separate from, and in addition to, your primary health or Medicare coverage. It isn’t paid to a hospital or provider. It’s paid to you, to use however you see fit, whether that’s medical bills, alternative treatment not covered, travel for treatment, household expenses, or lost income during recovery.
This is general product education. Specific covered conditions, benefit amounts, and waiting periods vary by plan and carrier. This page does not describe the details of any single policy.
What a Critical Illness Plan May Help With
- A lump-sum cash benefit paid upon diagnosis of a covered condition
- Out-of-pocket costs your primary coverage doesn’t fully absorb, such as deductibles and coinsurance
- Non-medical costs that come with a serious diagnosis, such as travel for treatment, home modifications, or everyday bills
- Commonly covered conditions include cancer, heart attack, and stroke, with some plans covering additional conditions, like loss of vision, paralysis, and more
If you’re approaching or on Medicare
A Serious Diagnosis Can Bring Costs Medicare Doesn’t Fully Cover
Whether you have Original Medicare, a Medigap plan, or a Medicare Advantage plan, a serious diagnosis can still come with costs beyond what your primary coverage absorbs, such as deductibles, coinsurance, or the daily copayments common on Medicare Advantage inpatient stays.
A critical illness plan is designed to work alongside your Medicare coverage, not replace it. It doesn’t change your Medicare benefits. It simply adds a cash benefit on top, to help offset the costs and disruptions that come with a diagnosis like cancer, a heart attack, or a stroke, at a stage of life when those diagnoses become more common.
If you’re on Medicare Advantage
A critical illness benefit can help offset copays and coinsurance tied to treatment for a covered condition.
If you’re considering Medicare Advantage
Pairing it with a critical illness plan is a common way to add a layer of financial protection against a major diagnosis while still benefiting from Medicare Advantage’s often lower premiums.
If you have Original Medicare and Medigap instead
A critical illness benefit can still provide a cash cushion for costs and expenses your Medigap plan doesn’t address.
Critical illness insurance is not a Medicare Advantage plan and is not a substitute for one. It does not replace or coordinate benefits with Medicare in the way Medigap does. Whether it makes sense alongside your specific Medicare coverage depends on that plan’s own cost-sharing structure.
Who this is for
Is a Critical Illness Plan Right for You?
- You’re on, or considering, a Medicare Advantage plan — Especially one with cost-sharing for major treatment or hospital stays
- You have a family history of a covered condition — Such as cancer, heart disease, or stroke, and want an added layer of financial protection
- You want a cash cushion, not just medical coverage — Benefits are paid to you directly, for you to use as needed
- You’re not yet Medicare-eligible — Under-65 individuals and families can also purchase critical illness coverage to help offset out-of-pocket costs from their own health plan
Why call Lifelong Insurance Agency
Finding the Right Fit for Your Situation
Critical illness plans vary in which conditions are covered, benefit amounts, and waiting periods before coverage begins. Since the right plan depends on your health history and how your Medicare coverage is structured, comparing options with someone who understands both sides matters.
Independent, not captive
We compare critical illness plans across multiple carriers, not just one.
No cost to you
Our guidance is always free, with no obligation to enroll.
We understand how it fits with your Medicare plan
We can look at your Medicare or Medicare Advantage coverage alongside critical illness options.
A resource beyond enrollment
We remain available to you for as long as you have coverage.
Carriers we represent
Backed by Trusted, Well-Known Insurance Companies
Because we’re independent, we’re able to compare plans from multiple reputable carriers, including:
…and other regional and national carriers, depending on your state
Carrier availability varies by state and plan type. This is not a complete list of every company we represent.
What clients say
Real feedback from people we’ve helped


Ready to Add a Layer of Protection?
Whether you’re already on Medicare or exploring your options, we’ll help you see whether a critical illness plan makes sense for your situation, with no cost or obligation.
Critical illness insurance is a supplemental policy and is not a substitute for comprehensive health insurance or Medicare coverage. Covered conditions, benefit amounts, waiting periods, exclusions, and eligibility vary by plan and carrier and are described in the policy itself. Pre-existing condition limitations may apply. This plan is not connected with or endorsed by the U.S. government or the federal Medicare program.